Home Author
Author

Micah Burke

Advertisement

HM Revenue and Customs has issued a fresh alert after revealing that around 827,000 young adults still have matured Child Trust Funds waiting to be claimed.

The average value of those accounts is now £2,310, meaning some people could have thousands of pounds sitting in their name without realising it.

The figures relate to Child Trust Funds — tax-free savings accounts that were created for children born between 1 September 2002 and 2 January 2011.

For some young adults, the account may have been opened so long ago that they have no memory of it at all.

And in cases where parents or guardians did not open one themselves, HMRC could have opened an account on the child’s behalf.

That is one reason why so many accounts remain untouched today.

827,000 accounts are still sitting there

According to HMRC’s latest figures, almost 3 million Child Trust Fund accounts belonging to 18 to 24-year-olds have already been claimed or transferred into an ISA since September 2020.

But around 827,000 matured accounts remain unclaimed.

The average balance of a matured Child Trust Fund still continuing as a CTF was £2,310 as of April 2026.

That does not mean every account contains exactly £2,310.

Some will hold less.

Others may be worth considerably more depending on the original contribution, later payments and how the money was invested.

But the scale of the unclaimed accounts means hundreds of thousands of people could still be unaware they have savings in their name.

Some people never knew the account existed

Child Trust Funds were introduced to give children a financial asset that could be accessed when they reached adulthood.

Parents or guardians were normally responsible for opening the account.

However, where that did not happen, HMRC could allocate a Child Trust Fund provider and arrange for an account to be opened automatically.

That means somebody who is now in their late teens or early twenties may have an account even if they have never personally seen paperwork relating to it.

The account matures when the holder turns 18.

At that point, the money belongs to them.

They can normally withdraw it, leave it invested or transfer it into another eligible account.

HMRC is actively trying to find the owners

The government has stepped up efforts to reconnect young adults with these forgotten accounts.

A Child Trust Fund Taskforce has been established to bring government and savings providers together, with the aim of reducing the number of matured accounts that remain untouched.

The oldest matured Child Trust Funds have now been sitting unclaimed for more than six years.

Economic Secretary to the Treasury Lucy Rigby said some young people may still not know that these savings are waiting for them.

The issue is not that the government is holding a pot of cash waiting to hand it out.

The money remains with banks, building societies and other Child Trust Fund providers.

The challenge for some people is simply discovering where their account is.
Pages: 1 2

Advertisement

A major shake-up of ISA rules has now been confirmed, with millions of savers under the age of 65 facing a new restriction on how much they can put into a Cash ISA each year.

From 6 April 2027, the annual Cash ISA limit for people under 65 will be cut to £12,000, down from the current position where the full £20,000 ISA allowance can be held in cash. The overall ISA allowance itself will remain at £20,000.

The move has attracted attention after being reported under Andy Burnham’s government, with the change set to alter the way many households use one of Britain’s most familiar tax-free savings products. The Manchester Evening News has also highlighted the new £12,000 rule in its coverage of the ISA changes.

The £20,000 allowance is staying — but there is a catch

At first glance, savers may see that the overall ISA allowance remains at £20,000 and assume little is changing.

But for anyone under 65, there is a major difference.

Under the current system, somebody can choose to place the full £20,000 annual ISA allowance into a Cash ISA.

From April 2027, they will no longer be able to do that.

Only £12,000 can go into Cash ISAs. The remaining £8,000 would need to be placed into another eligible type of ISA if the saver wanted to use the full £20,000 annual allowance.

That could mean Stocks and Shares ISAs, Innovative Finance ISAs or other qualifying ISA products, depending on the saver’s circumstances.

For people who deliberately prefer cash because they do not want investment risk, the distinction is significant.

Under-65s are the group directly affected

The new restriction applies specifically to people below the age of 65.

Those aged 65 and over will continue to have a £20,000 annual Cash ISA limit.

HMRC has confirmed that entitlement to the higher allowance will apply from the start of the tax year in which a person turns 65.

That creates a clear dividing line between younger and older savers under the new system.

A 64-year-old saver could therefore face a £12,000 Cash ISA ceiling, while someone covered by the 65-and-over rules could continue placing up to £20,000 into cash.

The government wants more money moved into investments

The change is not accidental.

HMRC says the policy is designed to encourage people to direct a greater proportion of their savings towards retail investments rather than cash.

The government argues that historical trends suggest investments can provide stronger long-term returns than cash savings, although investment values can fall as well as rise and returns are not guaranteed.

For many cautious savers, however, Cash ISAs have historically offered something quite different: straightforward tax-free interest without exposure to stock-market movements.

From April 2027, people under 65 who routinely save more than £12,000 a year into Cash ISAs will have fewer options if they want to remain entirely in cash within the ISA system.

There will also be tougher transfer rules

The government is also closing off routes that could otherwise be used to get around the new limit.

From April 2027, under-65s will not be allowed to transfer money from certain non-cash ISAs, including Stocks and Shares ISAs and Innovative Finance ISAs, back into a Cash ISA.

Transfers in the other direction — from a Cash ISA into a non-cash ISA — will still be allowed.

The intention is clear: savers will not be able to place money into an investment ISA first and then simply move it back into cash to bypass the £12,000 restriction.

Pages: 1 2

Advertisement

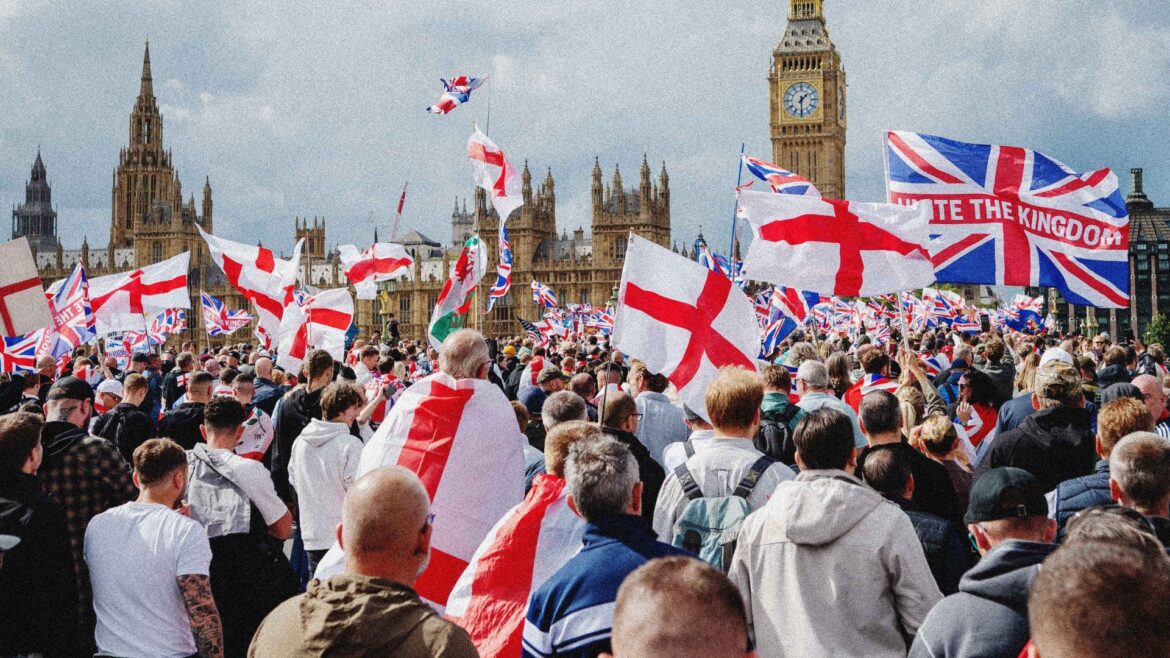
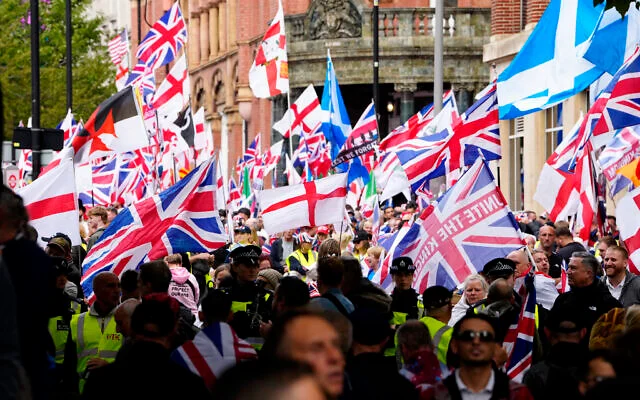
Massive independence protests have erupted across the UK! Thousands of demonstrators waving nationalist flags flooded the streets of Edinburgh, Glasgow, Cardiff, and Belfast, demanding immediate referendums to break away from the United Kingdom.

The spark? A historic “breakaway summit” in Cardiff, where regional leaders formed an unprecedented alliance against Downing Street. Here is everything you need to know about the mega-crisis threatening to tear the Union apart.

The Cardiff Summit: Three Regions vs Westminster

In mid-September 2026, the Welsh capital hosted a bombshell meeting. First Ministers and party leaders from Scotland, Wales, and Northern Ireland signed a joint pact demanding full self-determination.

The anti-Westminster front features:

  • John Swinney, SNP Leader and First Minister of Scotland

  • Rhun ap Iorwerth, Leader of Plaid Cymru

  • Michelle O’Neill, Sinn Féin Leader and First Minister of Northern Ireland

Their message to No 10 was brutal: London cannot block the will of the people forever, and “Westminster’s time is up.” The coalition issued a hardline joint declaration calling for three historic votes:

  1. A fresh Scottish Independence Referendum

  2. A landmark Welsh Independence Vote

  3. A Border Poll on Irish Reunification

London’s Counter-Strike: Referendums “Off Limits”

Downing Street hit back immediately. Prime Minister Andy Burnham initially suggested a Scottish referendum might be possible if there were “clear consensus.” However, Number 10 swiftly backtracked, declaring any new vote strictly “off limits.”

Regarding Northern Ireland, London remains firm: under the 1998 Good Friday Agreement, a border poll is only triggered if the Northern Ireland Secretary deems a majority vote likely. Ministers insist that threshold has not been met.

This brick wall from Westminster converted political friction into coordinated street action overnight.

Pages: 1 2

Advertisement

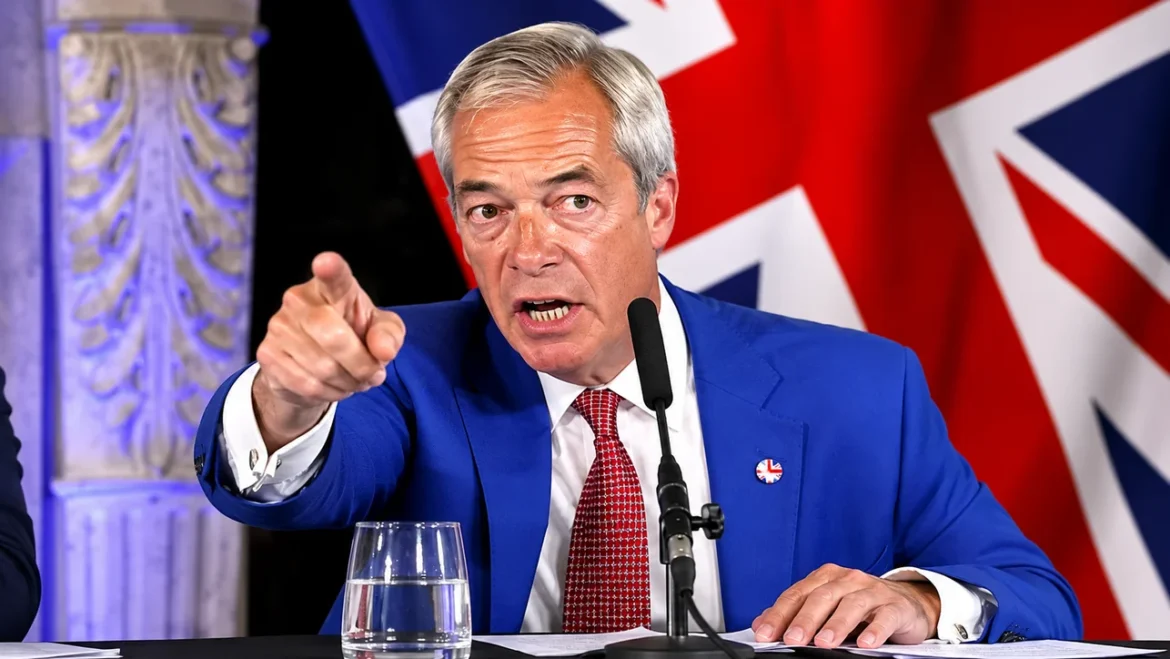
In early September 2026, BBC presenter Laura Kuenssberg conducted what instantly became the most fiercely debated interview of the political season. Her guest on Sunday with Laura Kuenssberg was Reform UK leader Nigel Farage, facing intense scrutiny over a burgeoning foreign donation scandal that threatened his party’s standing and his personal credibility. Kuenssberg’s persistent questioning, Farage’s contradictory defenses, and his remarkable admission that he “frankly wasn’t even listening” dominated headlines and set social media ablaze.

The Background: Undercover Footage and Foreign Funding Allegations

The high-stakes interrogation followed an explosive joint investigation by Channel 4 and investigative group Verbatim Investigations. Undercover recordings captured senior Reform UK figures—including Farage’s former chief of staff Dan Jukes and former director of policy James Orr—discussing methods to potentially bypass UK electoral laws prohibiting foreign political donations.

The footage appeared to show senior aides outlining channels to funnel tens of thousands of pounds from overseas donors through intermediaries. Following the revelations, both Jukes and Orr were removed from their roles. Opposition parties and media commentators immediately demanded formal investigations into Reform UK, with some calling for police intervention.

Against this backdrop, Farage’s appearance on BBC One became mandatory viewing across Westminster.

Key Flashpoints: Inside the Studio Interrogation

Kuenssberg opened the broadcast by challenging Farage on his oversight and knowledge of the recorded meetings. Farage’s response—asserting that he could not recall details and had “frankly not even been listening” to discussions between his aides and undercover reporters—was immediately seized upon by the presenter.

Kuenssberg highlighted the stark contradiction in his defense: Farage had long cultivated a reputation as a hands-on leader who understood campaign finance inside out, previously claiming to “know donation law better than anybody.”

1. “Are You Saying ‘Poor Me’?”

When Farage argued that Reform UK was the target of an orchestrated establishment smear campaign, Kuenssberg pushed back directly:

“It sounds like you’re simply saying ‘poor me’ — where is the actual evidence of a coordinated plot against you?”

The exchange went viral within hours, becoming a central takeaway across digital media.

Pages: 1 2

Advertisement

At the British Grand Prix in Silverstone on 5 July 2026, according to several online outlets and a viral spectator video, the Governor of the Bank of England, Andrew Bailey, and seven-time Formula 1 World Champion Lewis Hamilton were seen in the same paddock hospitality area. As Hamilton walked past, witnesses report that Bailey offered a handshake, but the driver kept moving and did not shake his hand.

The moment was not picked up by the official TV broadcast; the footage was captured on a mobile phone from the grandstands/viewing area and only began circulating heavily across social media and news sites several weeks later, in late August and early September 2026.

The incident occurred on race day, where Hamilton, driving for Ferrari, crossed the line in third place. Earlier in the weekend, he had taken sprint pole, but received a five-second penalty in the main race for a false start (stewards noted his car crept forward by 42 mm after the third red light and before the lights went out), ultimately missing out on the win to his teammate Charles Leclerc.

Against this backdrop, Hamilton was under intense media scrutiny, with journalists focussing on his penalty, the car’s balance, his battle with Leclerc, and the overall situation at Ferrari. In such a high-pressure environment, any unusual moment in the paddock—including a “snubbed handshake”—quickly turned into a talking point.

Pages: 1 2

Advertisement

The UK government is considering a new plan that could alter the country’s approach to the migration crisis. Under the proposed initiative, certain refused asylum seekers could be sent to third countries rather than their country of origin.

The topic took centre stage on a recent Matt Allwright show, where the presenter and panellists attempted to clarify whether such a measure could genuinely reduce the number of illegal English Channel crossings or if it would prove to be a repetition of the controversial Rwanda scheme.

Government representatives state that negotiations with several European and other nations are already under way. However, a definitive list of countries that might accept these individuals has not yet been determined. Core questions remain open: on what grounds decisions will be made, who will fund the accommodation, and whether London can execute such a policy within international law.

“Tough Signal” or a New Rwanda 2.0?

Proponents of the initiative believe the UK requires a stronger deterrent. In their view, if an individual knows they could be removed to a third country following a refusal, it could reduce the appeal of the dangerous Channel route.

During the broadcast, supporters argued that a portion of refused applicants cannot be returned home because the authorities of their home countries refuse to accept their own citizens. In such cases, advocates maintain that a third country offers a practical alternative to prolonged stays in British hotels and temporary holding centres.

Critics, however, compared the proposal to the Rwanda removal scheme. The previous scheme was scrapped in July 2024 following substantial costs and widespread legal disputes. Broadcast transcripts note that the programme cost British taxpayers hundreds of millions of pounds, despite resulting in only four voluntary removals.

Consequently, opponents fear the new initiative will prove expensive yet ineffective. Furthermore, they warn that transferring individuals to states with which they have no connection could pose serious risks to their safety and legal status.

Matt Allwright Clashes with Opposing Views

The discussion rapidly escalated into a clash between advocates for stricter migration enforcement and refugee rights defenders.

Some panellists insisted that individuals whose claims have been rejected must leave the UK. If their home country is unwilling to accept them back, placement in a safe third state is viewed as an acceptable resolution.

Others countered that an asylum refusal does not inherently mean a person poses a threat or is deliberately lying. An applicant may flee an unsafe nation while failing to meet the precise legal criteria for refugee status. In these cases, returns must be evaluated on an individual basis, accounting for specific circumstances.

The question of whether third-country removals breach human rights was particularly contentious. Critics argued that the UK should not “offload” its migration challenges by delegating responsibility to states over which London exercises no complete oversight.

Pages: 1 2

Advertisement

Nigel Farage has returned to Parliament after a decisive victory in Clacton.

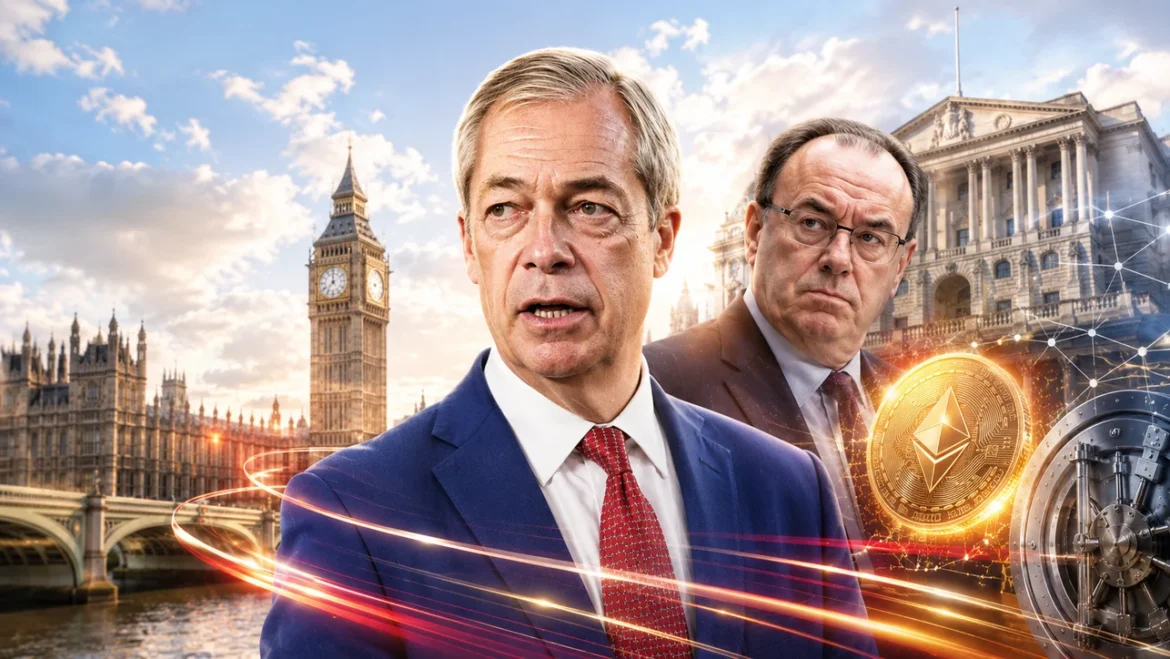
But the Reform UK leader is facing renewed questions over a remarkable chain of events involving a £5 million personal gift, Britain’s crypto rules and a private meeting with Bank of England Governor Andrew Bailey.

The key question is simple:

Why was Farage discussing stablecoin regulation with the country’s top financial official while his biggest donor was linked to one of the world’s most powerful crypto companies?

There is no finding that Farage broke the law or acted on behalf of Tether. Farage and Christopher Harborne have both said the money came with no strings attached.

But the timing of the meeting, the size of the donations and the financial interests involved have created a storm that Westminster has been unable to ignore.

THE DONOR BEHIND THE CRYPTO EMPIRE

Christopher Harborne is not an ordinary political donor.

He is a major shareholder in Tether, the company behind USDT — the world’s biggest stablecoin. Tether’s digital token is designed to maintain a value linked to the US dollar and is widely used as a bridge between the crypto market and traditional finance.

The company has become a giant in global finance. It is reported to hold vast quantities of US government debt and large reserves of gold, while operating with a remarkably small workforce compared with the scale of its business.

Harborne is understood to hold a substantial stake in the company.

He also donated £9 million to Reform UK in August last year, followed by another £3 million in October and £3 million in January. The donations were declared.

But the political controversy intensified after it emerged that Harborne had also given Farage a personal £5 million gift that was not registered at the time.

Farage has offered different explanations for the payment, describing it as an unconditional gift and saying it helped cover personal security and other costs.

The parliamentary standards investigation into the gift has now resumed following Farage’s return to Parliament.bbc.co+1

THE MEETING WITH ANDREW BAILEY

The most explosive part of the story centres on a conversation that took place between Farage and Andrew Bailey.

The Bank of England Governor has confirmed that Farage raised cryptocurrency regulation and central bank digital currencies during their meeting.

Farage reportedly made his position “very clear”.

He has long argued that Britain should embrace crypto and become a global centre for regulated digital finance. In a broadcast interview around the same period, he spoke enthusiastically about the scale of the stablecoin market and called for London to take a leading role.

The meeting took place while the Bank of England was considering tough restrictions on stablecoins.

Among the proposals under discussion were potential limits on how much individuals could hold — figures of between £10,000 and £20,000 had been reported during the consultation process.

For an industry built around the rapid expansion of digital currencies, restrictions of that kind could have had major commercial consequences.

That is why the conversation with Bailey matters.

Farage says he was expressing a long-standing policy position about the future of British crypto regulation. Reform insists that its policies were not shaped by individual donors.

The Bank Governor, meanwhile, has said he understands how to identify lobbying and knows how to take it into account.

But the question remains:

Was Farage simply arguing for a national policy — or could a change in British stablecoin rules also have benefited people connected to his biggest donor?

No evidence has established that Farage mentioned Tether directly during the meeting. That distinction is important.

Yet Tether was part of the wider financial background, and Harborne’s stake in the company made the potential conflict impossible to overlook.

Pages: 1 2 3

Advertisement

Nigel Farage has returned to Parliament after a dramatic victory in the Clacton by-election.

But the Reform UK leader’s comeback has been overshadowed by renewed questions about his financial affairs — including a reported £5 million personal gift from cryptocurrency businessman Christopher Harborne.

Farage insists he has followed the rules and declared his outside work. Yet critics say the latest disclosures raise more questions than they answer.

And now the parliamentary standards investigation has resumed.

‘THEY CAN’T STAND HIS SUCCESS!’

Supporters of the Reform leader say the Westminster establishment is attacking Farage because he has built a successful career outside politics.

New figures reported in August suggest that he earned more than £2 million from television work, speaking engagements, writing and other activities during his first two years as an MP.

Farage’s defenders argue that the money was earned openly and that voters should be free to choose MPs with real-world experience rather than career politicians who have never worked outside Westminster.

They also point to the apparent contrast between Farage’s declared broadcasting income and the political outrage surrounding it.

The message from his supporters is clear:

If the earnings were declared, what exactly is the scandal?

BUT THE QUESTIONS HAVE NOT GONE AWAY

The controversy is not limited to Farage’s television appearances or public speaking work.

The parliamentary standards commissioner has been examining whether certain financial interests and benefits should have been registered under the Commons’ rules.

One of the most closely watched issues is a reported £5 million gift linked to Christopher Harborne. Political opponents have also raised questions about other financial connections surrounding Reform UK.

No finding of wrongdoing has been established. But the investigation’s return means the issue is unlikely to disappear after Farage’s election victory.

Instead, his return to Parliament has placed the controversy back at the centre of British politics.

THE ELECTION THAT CHANGED EVERYTHING

Farage triggered the Clacton by-election after resigning his seat. He presented the contest as a direct test of public confidence in Reform UK and a chance to silence his critics.

He won the vote with 63% of the ballot, while novelty candidate Count Binface came second with around 27%.

But Farage did not attend the count. He said police had warned him about a possible attempt to disrupt the result.

His supporters described the decision as sensible. Opponents saw it as an extraordinary absence from the very election he had forced.

Either way, the victory gave Farage a fresh parliamentary mandate — while simultaneously reviving the financial investigation that had been paused after his resignation.

Pages: 1 2

Advertisement

Most people in the UK still see their bank as a place to pay bills, stash cash and maybe open a basic savings account. Yet, quietly sitting behind the same online banking logins, several high street banks now run fully‑fledged investment platforms – and only a small minority of Britons are actually using them. While social media is full of ads for “secret trading apps” and “AI bots” that claim to turn £200 into £20,000 in weeks, the boring bank‑backed platforms are growing slowly, steadily – and under strict UK regulation.theinvestorscentre.co

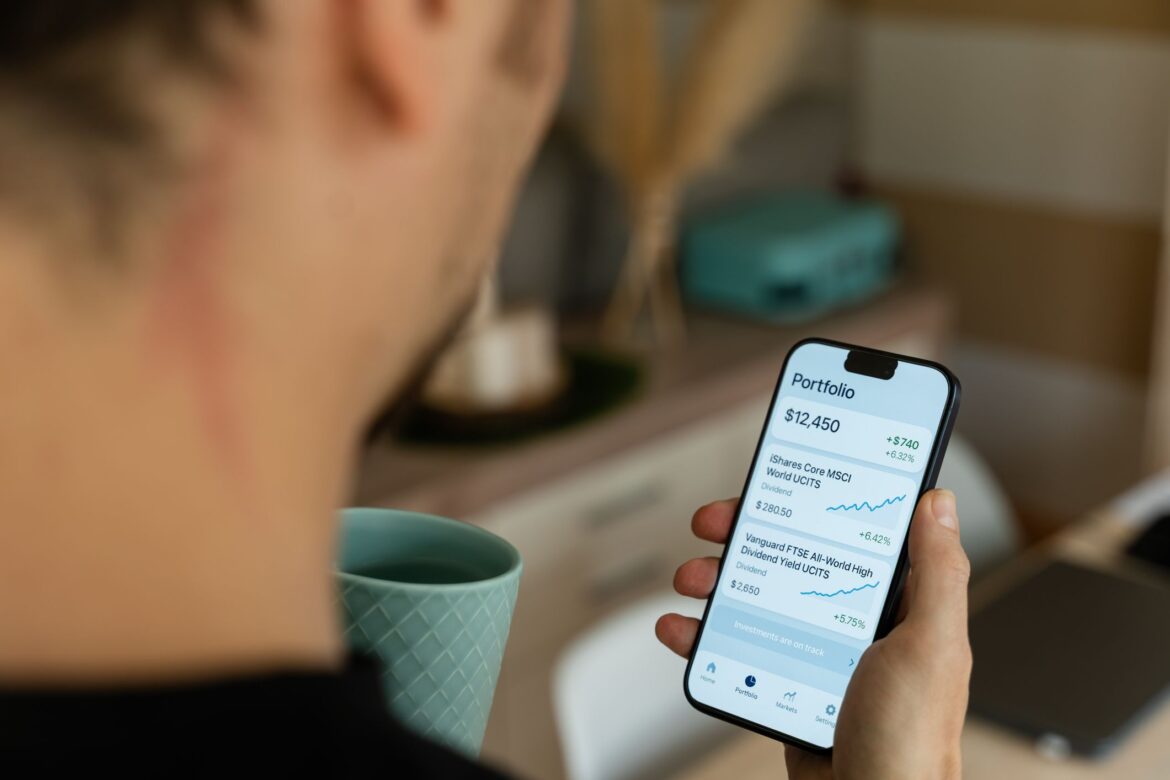
These services let you buy funds, shares and ETFs directly through your usual bank, under the supervision of the Financial Conduct Authority (FCA) and with potential protection from the Financial Services Compensation Scheme (FSCS) up to £85,000 per eligible person, per firm if the provider fails. For cautious savers who want their money to work harder without gambling on unregulated schemes, that’s a completely different level of comfort.theinvestorscentre.co

What exactly is a bank investment platform?

Think of a bank investment platform as an “investing tab” inside your online banking. Instead of signing up to a separate app, you log in as normal and see extra sections such as a Stocks & Shares ISA, a general investment account or even a SIPP (Self‑Invested Personal Pension). From there, you can choose investments, set up regular contributions and track performance alongside your everyday spending.

Here are three of the most important platforms that already exist inside major UK banks:

  • HSBC – Global Investment Centre
    HSBC runs the Global Investment Centre – an online fund platform where customers can research, buy and monitor a wide range of funds via online and mobile banking. You can invest from relatively small amounts, set up regular monthly payments and manage everything in the same HSBC interface you already know.hsbc.co

  • Lloyds Bank – Investment Platform & Share Dealing ISA
    Lloyds offers an entire Investing section with a Share Dealing ISA, general investment accounts and SIPPs. Clients can either pick individual shares and ETFs or use ready‑made portfolios. Independent reviews highlight low fixed platform fees and free regular investing for certain products, making Lloyds one of the cheaper “big name” options for long‑term investors.hsbc.co+1

  • NatWest – NatWest Invest
    NatWest Group runs NatWest Invest – a digital investment platform built around simple, managed portfolios rather than DIY stock picking. You answer a few questions about your goals and risk level, and the service suggests a portfolio that is then managed on your behalf. As with the other platforms, NatWest Invest is authorised and regulated by the FCA and eligible for FSCS protection, subject to the usual limits.theinvestorscentre.co

All three examples above are well‑known UK banks, operating under UK rules, not offshore entities with unclear ownership.

Why do so few Britons use them?

Despite being widely available, these platforms are still used by a minority of customers. There are a few reasons:

  • They don’t shout about “get rich quick”. The marketing is conservative, full of “capital at risk” disclaimers and details of platform fees. That’s the opposite of the loud, emotionally charged ads for unregulated trading schemes – so they simply don’t cut through on social media.

  • The jargon is intimidating. Terms like “Stocks & Shares ISA”, “GIA” and “SIPP” sound like products for professionals only. In reality, opening a Lloyds Share Dealing ISA or similar account is an online form that most people can complete in a few minutes, if they have a National Insurance number and a UK bank card.

  • The British love of cash. Many savers still prefer cash ISAs and fixed‑rate bonds because the return is known in advance. But with inflation, relying solely on cash means your real spending power may shrink, especially over 10–20 years.

Pages: 1 2

Advertisement

GCHQ Director Warns of Technological Threat

British intelligence is developing a new cyberdefence system designed to respond to attacks at machine speed. At the heart of the project is agentic artificial intelligence capable of autonomously detecting threats, analysing data, and assisting in fending off attacks on critical national infrastructure.

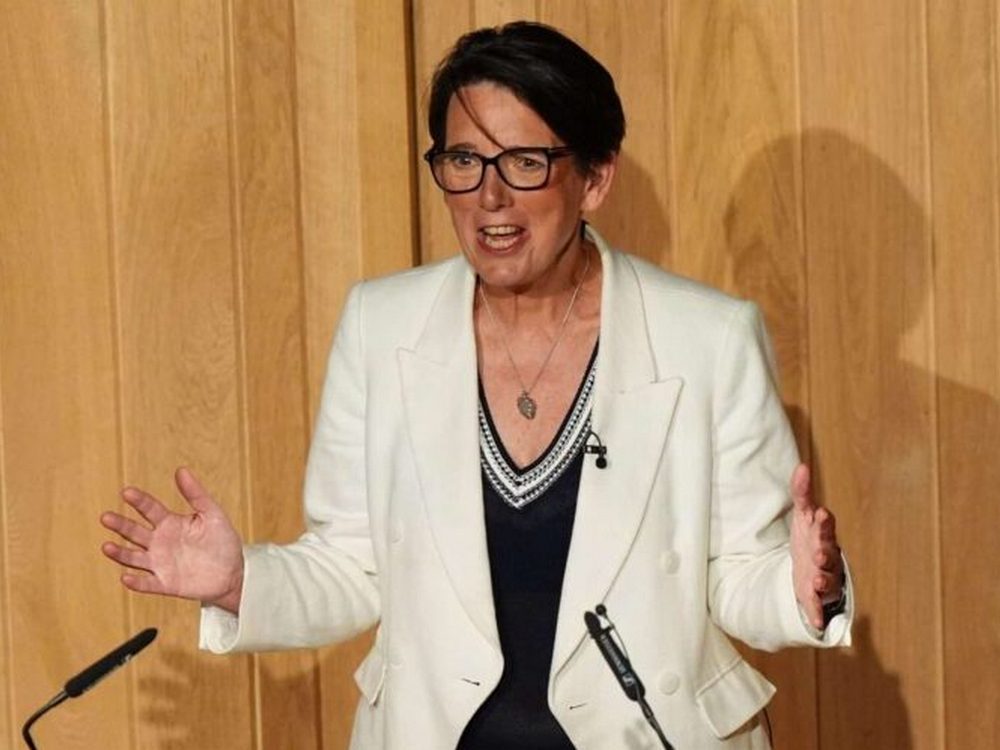
The initiative was outlined by GCHQ Director Anne Keast-Butler during her annual lecture at Bletchley Park. She declared that artificial intelligence has become an “unprecedented force” that must be harnessed, while simultaneously warning of the risks surrounding its proliferation and military application.

Her speech served as a stark warning to both government and business. According to the GCHQ chief, the UK and its allies are rapidly approaching a tipping point where their technological edge could evaporate. If state systems defend themselves more slowly than adversaries generate new attack vectors, even major corporations or vital infrastructure could be left exposed.

Cyberattacks Outpacing Human Reaction Time

Traditional cyberdefence relies heavily on human analysts to spot suspicious activity, verify data, and decide on a response. While effective against conventional threats, this model is dangerously slow in a world where threat actors leverage automation and AI.

The new system outlined by Keast-Butler aims to embed cutting-edge agentic AI directly into the UK’s national cyberdefence posture. These agentic systems will monitor suspicious signals, cross-reference them with wider events, identify indicators of coordinated attacks, and feed actionable intelligence to defenders in near real-time.

The technology is expected to safeguard critical national infrastructure, airlines, telecoms networks, and major commercial enterprises. GCHQ views the initiative as a paradigm shift in national defence, shifting the focus from post-breach mitigation to intercepting attacks while they are still taking shape.

In essence, British authorities are seeking to construct a digital shield that continuously scans national systems for threat indicators. The faster AI detects suspicious behaviour, the narrower the window for adversaries to breach networks, exfiltrate data, or disrupt essential services.

An “Unprecedented Force” with Dangerous Consequences

The most striking part of Keast-Butler’s address focused not on AI’s capabilities, but on its grave risks. She warned that AI is already being deployed by criminals and state adversaries to supercharge cyberattacks, fraud, disinformation, and malicious campaigns.

Leveraging AI allows actors to craft convincing phishing emails at speed, pinpoint system vulnerabilities, refine ransomware strains, and amplify deceptive narratives. Tasks that once required a team of specialists and months of preparation can now be executed faster and on a far greater scale.

GCHQ also highlighted the danger of AI being used in sub-threshold operations—actions falling short of open warfare. This includes infrastructure disruption, manipulating public sentiment, targeting businesses, and attempting to erode trust in public institutions.

This is precisely why the intelligence chief frames AI not merely as a new tool, but as a force capable of reshaping the rules of conflict. AI does not need to launch missiles or command troops to inflict severe damage; crippling communications networks, disrupting transport, targeting power grids, or paralyzing digital services is more than enough.

Pages: 1 2

Advertisement

Newer Posts
logo-white

Contact information

Disclaimer

The information provided on this blog is for general informational and entertainment purposes only. All content reflects personal opinions and experiences and should not be considered professional, legal, financial, medical, or other specialized advice. While efforts are made to keep the information accurate and up to date, no guarantees are made regarding completeness, reliability, or accuracy.

All rights reserved © 2026